What Actually Happens During a Life Insurance Exam
What Actually Happens During a Life Insurance Health Exam
Most people who put off applying for life insurance are not hesitating about the coverage itself. They are hesitating about the exam. A friend or family member mentioned a phone call, someone showing up at the house, a blood draw, but the actual details get fuzzy fast, and that uncertainty alone is often enough to delay applying for months. The exam is not a test with a pass-or-fail grade attached to it, and it is not the ordeal it sometimes gets built up to be. It is a short, routine appointment built around a specific set of numbers and answers, and those numbers are what an underwriter uses to land on a rate class. Here is what actually happens, step by step, from the knock on the door to the decision that follows.
Who shows up, and where it happens
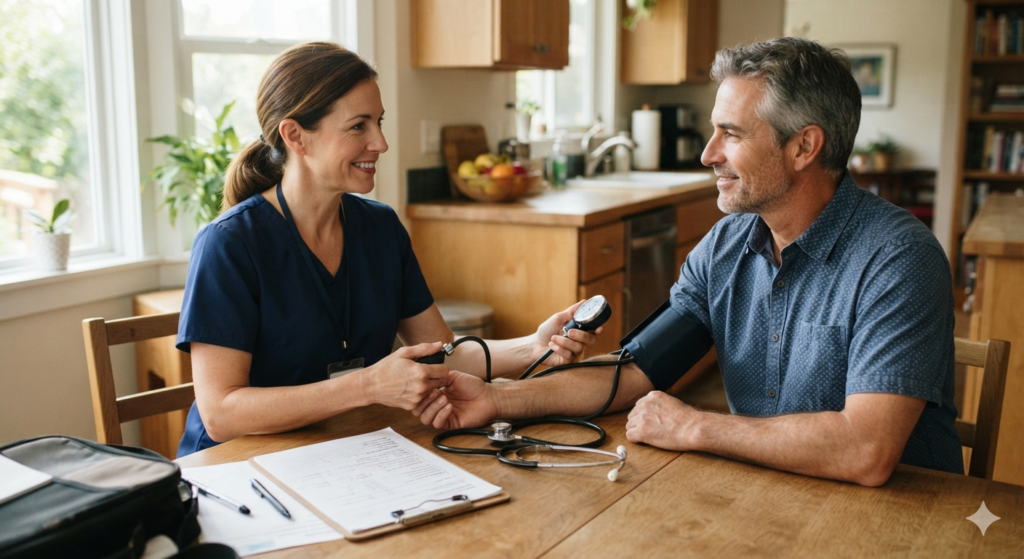
A paramedical examiner handles the exam itself, not the agent, and not a doctor employed by the insurance company. This person works for a separate company that specializes in health screenings built specifically for insurance applications, and the same handful of these companies handle appointments for most major carriers, so the process feels the same regardless of which company is underwriting the policy. They travel to wherever is easiest: a kitchen table at home, a break room at work, sometimes a local clinic if that is more convenient for the schedule. The appointment gets booked around the applicant’s calendar, including evenings and weekends in many cases, usually within a few days of applying, and the whole visit typically runs twenty to thirty minutes start to finish. Rescheduling is normal too; if the timing does not work, a quick call to the examiner’s scheduling line usually finds a new slot within a day or two.
What to have ready before they arrive
- A photo ID
- A current list of medications, with dosages if possible
- Contact information for the applicant’s primary doctor
Having these three things ready before the examiner arrives is what keeps the appointment moving instead of stretching into extra paperwork afterward.
What gets measured during the exam
The examiner starts with the basics, height, weight, blood pressure, and pulse, then moves to a blood draw and a urine sample. Both samples get shipped out to a lab and checked for things like cholesterol, blood sugar, kidney and liver function, and nicotine markers. None of this is a full diagnostic workup the way an annual physical might be; it is a targeted snapshot built to answer a narrow set of questions an underwriter actually needs answered. A single high blood pressure reading on exam day, for example, does not automatically drop someone into a worse rate class. Underwriters typically look at the whole picture, including any blood pressure history already on file with a doctor, before making that call.
Why the blood and urine tests carry so much weight
These two samples do more underwriting work than any other part of the exam. Cholesterol and blood sugar numbers point toward cardiovascular risk and diabetes. Nicotine markers confirm whether someone is genuinely tobacco-free, since tobacco use changes pricing substantially, even for someone who only smokes occasionally or uses a vape instead of cigarettes. Kidney and liver values can flag something an applicant may not even know about yet. Because so much rides on these two samples, a clean set of labs can sometimes speed up the entire decision, while an unexpected result can trigger a request for more information before a final answer comes back.
Questions that go beyond the paperwork
The exam is not only about measurements. The examiner typically confirms the health history answers already given on the application, walks through family medical history, including whether parents or siblings had heart disease, cancer, or diabetes and at what age, and often asks about occupation, hobbies, and any recent travel. This is not about catching someone in a mistake, it is about making sure everything lines up before the file moves to underwriting. A mismatch between what was written on the application and what gets said out loud during the exam, like forgetting to list a medication or leaving off a doctor’s visit from earlier in the year, is one of the more common reasons a file gets pulled aside for extra review. It is worth taking a few minutes beforehand to double-check that the application was filled out completely and accurately.
How the results factor into the underwriting decision
Once the exam wraps up, the lab results and the examiner’s notes get attached to the application and sent to underwriting. Depending on the carrier and what shows up in the results, the underwriter may also run a quick lab-based risk check or request medical records directly from a doctor’s office, usually for a chronic condition or something the exam flagged that the application alone does not fully explain. That records request goes straight to the doctor’s office, not to the applicant, and it can add real time to the process since medical offices do not always treat it as urgent. None of these pieces get weighed in isolation. The underwriter looks at everything together to land on a rate class, and a clean exam does not guarantee the best possible rate any more than one unusual result guarantees a worse one. It is genuinely a full-picture decision, not a single pass-or-fail moment. Anyone with questions about how a specific health condition might factor in is usually better off asking a licensed life insurance agent before the exam, rather than guessing.
What can slow things down after the exam
Lab processing typically takes anywhere from a few days to about two weeks, depending on the lab and how backed up it is that month. Files move quickly when nothing unexpected turns up, no flagged labs, no outside records needed, no gap between what the application said and what the exam confirmed. Files slow down when a chronic condition is involved, when a doctor’s office is slow to respond to a records request, or when a lab value needs a second look before anyone signs off on it. Anyone waiting longer than expected should not assume the worst, since most delays have a specific, explainable cause. A licensed life insurance agent can usually check in with the underwriting team directly and find out exactly where a file stands and what, if anything, is still outstanding.


