How Cash Value Grows in a Permanent Life Policy
A permanent life insurance policy does two jobs inside the same contract. Part of every premium payment covers the cost of the death benefit, the same as a term policy. The rest goes into a separate account inside the policy called cash value, which grows on its own schedule for as long as the policy stays in force. That growth isn’t tied to a savings account interest rate or the stock market’s daily swings. It follows rules set by the policy type itself, whether that’s a guaranteed minimum written into a whole life contract, a crediting rate declared by the insurer on a universal life policy, or a formula tied to a market index with a cap and a floor. Knowing which set of rules applies to a specific policy explains most of what shows up on an annual statement.
Where the Premium Dollar Actually Goes
Every premium payment on a permanent policy is split into pieces before any of it reaches the cash value account. A portion covers the cost of insurance, which is the actual price of the death benefit for that policy year, based on the insured’s age and health at issue. Another portion covers administrative fees and, in some policy designs, a share of the insurer’s own overhead. What’s left after those costs are subtracted is what gets added to cash value. In the first several years of a policy, the cost-of-insurance piece and the fee piece take up a larger share of each payment, which is one reason cash value tends to build slowly at first. As the policy matures and some of the upfront costs have already been paid, a larger share of each premium dollar starts flowing into cash value instead. This is also why surrendering a permanent policy in the first few years typically returns very little cash, even though premiums have been paid the whole time.
Reading the Cost of Insurance Line on a Statement
Most annual policy statements list the cost of insurance as its own line item, separate from any dividend or interest credited that year. That number typically rises slightly each year as the insured ages, since the underlying mortality cost increases with age even though the death benefit and premium may stay level. Comparing that line from one year to the next is a useful way to see exactly how much of a premium payment is actually going toward the insurance itself versus how much is building cash value.
How the Growth Rate Is Actually Determined
The mechanics behind cash value growth depend on which type of permanent policy is in force. A whole life policy typically includes a guaranteed minimum interest rate written into the contract, along with the possibility of non-guaranteed dividends declared annually by the insurer based on its overall financial performance. A universal life policy instead credits interest at a rate the insurer sets periodically, often loosely tied to current market conditions, with a guaranteed floor below which the rate cannot fall. An indexed universal life policy ties growth to the performance of a market index, such as a stock index, but with a cap limiting the maximum credited rate in a strong year and a floor, often zero, protecting against a loss in a down year. None of these designs invest cash value directly in the stock market the way a brokerage account would. The index-linked version uses the index’s performance only as a reference point for calculating that year’s credited rate. Understanding which of these three structures applies to a specific policy is the difference between a realistic expectation for how the cash value will grow and a surprised phone call at renewal time.
Guaranteed vs. Non-Guaranteed Growth
Every permanent policy separates its growth into a guaranteed piece and a non-guaranteed piece. The guaranteed piece, whether a minimum interest rate or a fixed schedule of values, is the number a policy will reach no matter what happens with dividends or market performance. The non-guaranteed piece, like a dividend or a rate above the floor, depends on factors outside anyone’s control and can move up or down from year to year. Policy illustrations typically show both figures side by side, and asking to see both columns clearly laid out, rather than just a single projected total, is a reasonable request of any agent presenting one.
Why Growth Is Slow in the Early Years
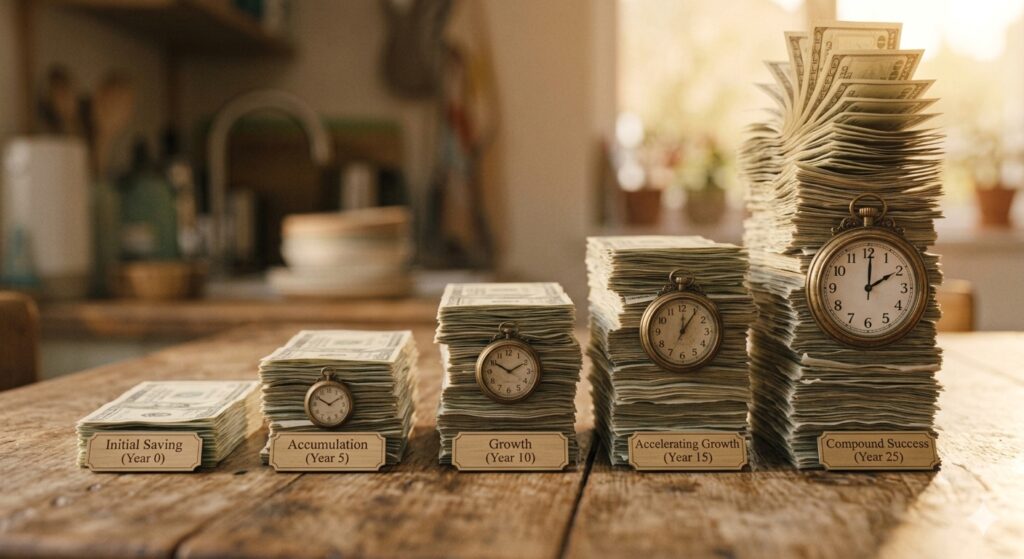
Cash value in a new permanent policy almost always grows more slowly than people expect in the first several years, which often surprises new policyholders. Beyond the cost-of-insurance and fee structure already built into each premium, many policies also apply a surrender charge schedule during the early years, which reduces the amount available if the policy is canceled or heavily withdrawn from during that window. That charge typically declines gradually and disappears entirely after 10 to 15 years, depending on the policy. Dividends on whole life policies, when they’re paid at all, are also usually smaller in early years relative to the size of the policy, since they’re often calculated in part based on how much cash value has already accumulated. None of this means the policy is underperforming. The growth curve on a permanent policy tends to look flat at first and steeper later, worth knowing before judging its performance from a statement in year two or three.
How Living Benefits and Loans Interact With Cash Value
Cash value isn’t just a number sitting on a statement. It can typically be borrowed against or withdrawn from while the policyholder is alive, which is part of what a living benefits feature refers to. A policy loan uses the cash value as collateral rather than removing it from the policy outright, and the loan accrues interest, meaning an outstanding loan balance can reduce both the death benefit and future growth if it isn’t repaid. A withdrawal, where the policy design allows one, permanently reduces the cash value and may reduce the death benefit as well. Some permanent policies also include riders that let a portion of the death benefit be accessed early in the case of a qualifying serious illness, which draws against that same underlying value rather than being a separate pool of money. Reaching out to an agent familiar with the specific policy’s rider language before assuming how much is actually accessible, and under what conditions, can prevent an unpleasant surprise if that feature is ever needed.
What Actually Moves the Growth Number Year to Year
The figure that changes on a cash value statement from one year to the next is usually the result of several moving parts working together rather than one simple interest calculation. A dividend declared at a lower rate than the previous year, a universal life crediting rate that dropped closer to its guaranteed floor, or an indexed policy that hit its cap in a strong market year can all produce very different-looking results even within the same policy type. An outstanding policy loan will also reduce the growth shown, since interest continues accruing against the loan balance even as new premium and any credited interest are added elsewhere in the account. Reviewing the annual statement line by line, rather than just the bottom-line total, shows why a number moved the way it did. Asking an agent to walk through that statement once a year, ideally alongside a broader coverage review, turns cash value from a mysterious figure into something a policyholder can track and plan around.


